
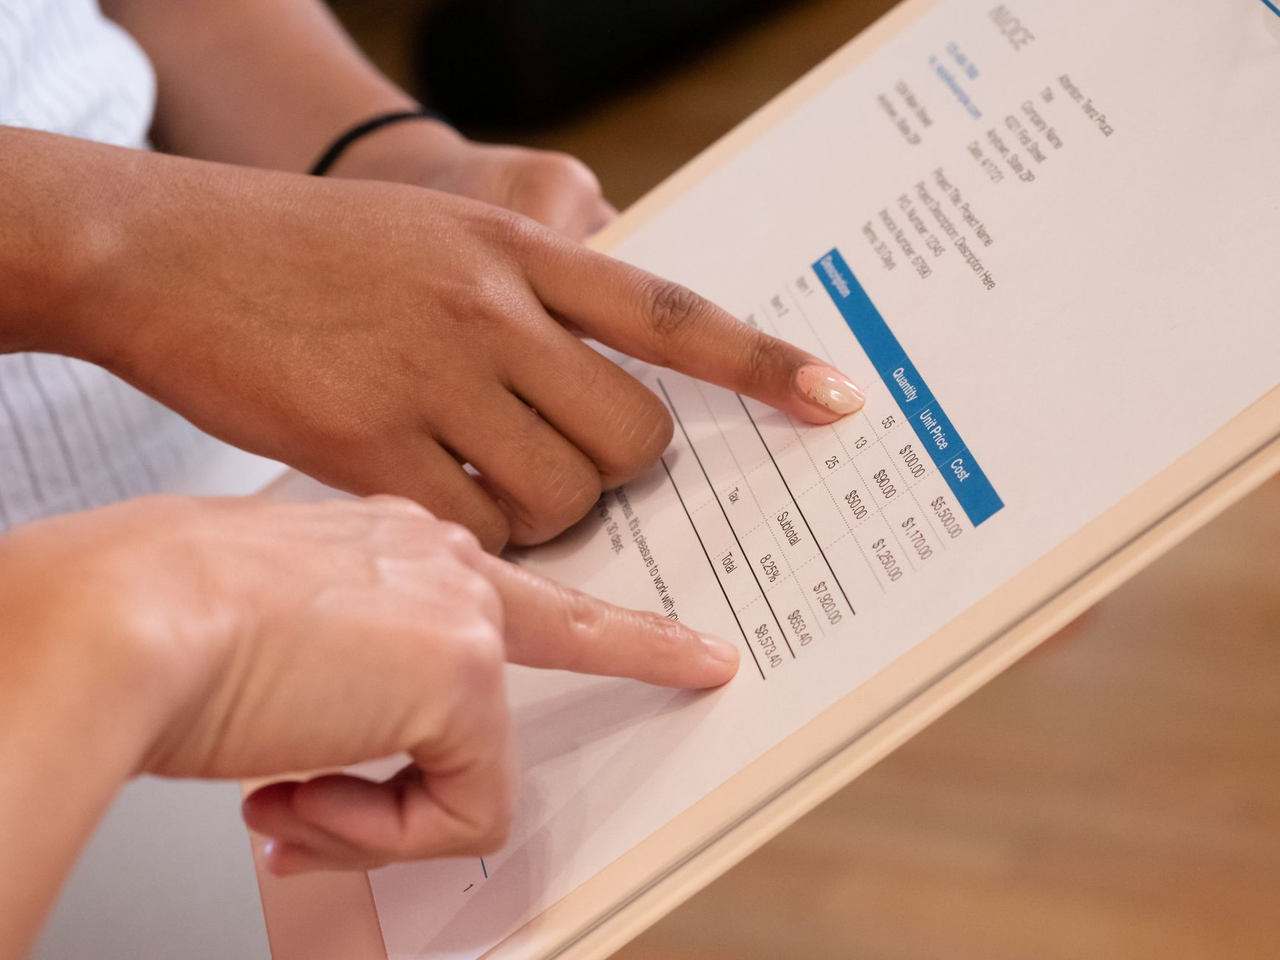
A shoebox of receipts works fine for a business with a dozen customers. It stops working the month a founder realizes she can’t say which invoices are overdue, whether last quarter’s software subscriptions were ever categorized, or why the bank balance doesn’t match the spreadsheet. Nothing dramatic happened. The business simply grew faster than the habits holding its records together, and the gap shows up at the worst moments: tax time, a loan application, a hiring decision.
Why Financial Records Slip as Companies Grow
Early on, one person remembers everything. A growing company breaks that arrangement. Invoices go out from three places, expenses arrive as photos in text messages, and the person who “does the books” is also the owner, the salesperson and the customer service desk.
Bookkeeping is rarely hard. It is relentless. Entries have to be made weekly, accounts reconciled monthly and receipts matched before they vanish. When that rhythm breaks, a small backlog turns into a cleanup project, and cleanups cost more than steady upkeep ever did.
Getting Help With the Routine Work
Owners usually reach a point where the finance chores crowd out everything else. Many then look at an accounting virtual assistant as a way to keep the routine moving without hiring a full-time employee. An accounting virtual assistant works remotely on defined, repeatable tasks under the owner’s direction. VirtuDesk, for example, says its assistants can help with bookkeeping, monthly invoicing, banking, accounts receivable and accounts payable management, and monthly and quarterly expense reporting and reconciliation. Its page also lists administrative support such as organizing documents and managing schedules. It doesn’t publish pricing or contract terms on that page, so ask about them directly on a discovery call.
One point matters here. A remote assistant handles the processing. Decisions about tax strategy, financing and how the numbers are reported should stay with you and a qualified accountant.
The Cost of Slow Invoicing
The invoice is where records and cash meet. According to Intuit QuickBooks research cited in a Forbes Finance Council column, 56% of U.S. small businesses were carrying unpaid invoices, with an average of $17,500 tied up in accounts receivable. The column’s author works for Intuit QuickBooks Payments, so read it as an industry view rather than a neutral study. The point still holds. Money owed is only useful once it’s collected, and collection depends on invoices that are accurate, sent promptly and followed up on a schedule.
What to Hand Off and What to Keep
| Task | Examples | Hand off? |
|---|---|---|
| Invoicing | Preparing and sending invoices on a set schedule | Yes, with a template and approval rules |
| Receivables follow-up | Reminder emails, tracking overdue accounts | Yes, with a script for tone and escalation |
| Payables | Entering bills, scheduling payments for your approval | Yes, if you approve the payment run |
| Expense tracking | Categorizing transactions, matching receipts | Yes |
| Reconciliation | Matching bank and card activity to the books | Yes, with a monthly review by you |
| Monthly reporting | Preparing summaries for your review | Partly. You or your accountant interpret them |
| Tax filing and strategy | Returns, deductions, planning | Keep with a qualified accountant |
| Banking authority | Signing, moving large sums | Keep with the owner |
Matching the Role to the Need
The labels overlap, and providers use them loosely, so ask what a person has actually done rather than relying on the title.
| Role | Typical focus | Fits a business that… |
|---|---|---|
| Bookkeeping virtual assistant | Daily entries, invoicing, expense coding | Needs steady, hands-on upkeep |
| Bookkeeper virtual assistant | The same work, often with ledger and reconciliation experience | Has records to clean up or reconcile regularly |
| Virtual bookkeeper | Ownership of the books on a recurring schedule | Wants one person responsible for accuracy |
| Accounting virtual assistant services | A mix of finance and admin support | Needs help across invoices, scheduling and documents |
Choosing How to Get Bookkeeping Done
Do it yourself. Cheap in cash, expensive in attention. It works while volume is low, and it tends to fail during busy weeks.
Hire in-house. You get a dedicated person and deep company knowledge, along with salary, benefits and a single point of failure when they’re out.
Use remote services. With remote bookkeeping services, a provider supplies the person and handles matching and replacement. Ask about set-up fees and minimum terms before you sign.
Try a firm.Outsourced bookkeeping services from an established firm can bring a team and review layers, which suits larger volumes, though it may be less flexible on small, odd tasks.
Many owners searching for bookkeeping support for small businesses land on a managed remote arrangement, because they rarely have time to recruit and train someone.
Protecting Your Financial Data
Financial records are sensitive, so set limits before anyone sees real accounts. Use a password manager instead of shared logins, turn on two-factor authentication, and prefer view-only or limited roles in your accounting software over full admin rights. Never share the owner’s banking credentials when a restricted login can do the job. Put confidentiality terms in writing, and keep the authority to approve payments with someone you trust.
Building a Routine That Lasts
Pick a Weekly Rhythm
Set aside the same slot each week for invoices, receipts and bank entries. Small, regular work beats a monthly marathon.
Standardize Your Inputs
Agree on how receipts arrive, how expenses are categorized and what an approved invoice looks like. Most bookkeeping errors start with unclear inputs.
Review Before You Trust
Look at the monthly reconciliation yourself, or ask your accountant to. A quick review catches the miscoded charge before it becomes a tax-season surprise.
Questions to Ask Before You Commit
- Which tasks are included, and which accounting tools will be used?
- How are people vetted, trained and replaced if they leave?
- What are the set-up fees, minimum terms and cancellation rules?
- How is financial data protected, and who has access to my accounts?
- What reporting will I receive, and how often?
- Who is accountable for errors, and how are they corrected?
Frequently Asked Questions About Managing Business Financial Records
What can an accounting virtual assistant do for a small business? It can prepare invoices, follow up on overdue payments, track expenses, enter bills and support reconciliation. These are repeatable tasks with clear steps. Tax advice, financing decisions and final sign-off should stay with you and a qualified accountant.
Is a virtual bookkeeper the same as an accountant? No. A bookkeeper records and organizes transactions, while an accountant interprets the numbers, advises on tax and financial strategy, and prepares filings. Many growing businesses use both, with bookkeeping handled day to day and an accountant reviewing periodically.
When should a growing business outsource bookkeeping? Consider it when records fall behind, invoices go out late, or finance work regularly crowds out sales and service. Starting before a backlog builds is easier and cheaper than cleaning one up later.
Is it safe to give a remote assistant access to financial records? It can be, with controls. Limit access to what the task needs, use a password manager and two-factor authentication, avoid sharing owner-level banking credentials, and sign confidentiality terms. Review activity regularly, especially at the start.
How do I know the arrangement is working? Track measurable results: how quickly invoices go out, how many remain overdue, whether reconciliations finish on schedule and how few errors your review catches. If results slip, check the instructions before changing the person.